TL;DR
Your account balances may not equal the money you could actually spend. Pretax retirement accounts can create future income-tax bills, taxable investments may contain gains that become taxable when sold, and rental property can carry tax consequences linked to past depreciation deductions. For everyday tracking, use current balances. For long-term planning, calculate an additional after-tax view and include taxes already owed as liabilities.
The Hidden Tax Liabilities That Could Be Reducing Your Net Worth
Your Net Worth May Be Overstated — Here’s Why
A standard net worth calculation is simple:
Net Worth = Total Assets − Total Liabilities
That formula is still correct. The complication is that some assets carry future tax consequences that do not appear beside the current account balance.
A traditional 401(k) showing $600,000 is a real asset, and it belongs in a standard net worth statement. But pretax amounts withdrawn in retirement are generally taxable income. A brokerage account worth $300,000 is also a real asset, but part of that value may be an unrealized gain that becomes taxable after a sale. An investment property may contain equity on paper while future sale proceeds are reduced by taxes connected with depreciation deductions.
This does not mean your ordinary net worth calculation is wrong. It means it answers one question: what are your assets worth before future taxes? Retirement and sale planning need a second question: what might remain after taxes are paid?
Hidden Tax Liability #1: Pretax Retirement Accounts
Traditional 401(k) and traditional IRA balances are often among the largest assets on a household balance sheet. The tax advantage comes upfront: eligible pretax contributions may reduce taxable income during working years, and investment growth is generally not taxed annually inside the account.
The tax bill usually appears later. According to the IRS, distributions from pretax 401(k) amounts, including earnings, are generally included in taxable income when withdrawn. Traditional IRA tax treatment can depend on deductible and nondeductible contributions, so not every traditional IRA dollar is automatically taxable in the same way.
Suppose you have $600,000 in fully pretax retirement savings and estimate that withdrawals will face an average federal income-tax rate of 22%:
| Retirement Asset View | Amount |
| Current pretax retirement balance | $600,000 |
| Estimated future federal tax at 22% | -$132,000 |
| Estimated after-federal-tax value | $468,000 |
For monthly net worth tracking, it is reasonable to record the full $600,000 current balance. For retirement spending projections, the $468,000 after-tax estimate may be more useful.
Use an estimated effective tax rate for future withdrawals rather than automatically applying today’s highest marginal bracket. Retirement withdrawals may be spread across years, and your future taxable income, state residence and tax rules can change.
Roth accounts require different treatment. Qualified Roth withdrawals are generally tax-free, so a qualified $600,000 Roth balance may offer more future spending power than the same amount held in a fully pretax account.
Hidden Tax Liability #2: Unrealized Gains in Taxable Brokerage Accounts
A taxable brokerage account can also contain a tax bill that has not yet been triggered.
Suppose your investment account is worth $300,000, and your cost basis — what you paid for the investments, adjusted where required — is $220,000. You have an unrealized gain of $80,000.
You do not generally owe capital-gains tax simply because the account increased in value. The tax issue usually arises when you sell investments at a gain.
For long-term gains, federal tax rates are generally 0%, 15% or 20%, depending on taxable income and applicable rules. Assuming a 15% federal long-term capital-gains rate:
| Taxable Investment View | Amount |
| Brokerage account value | $300,000 |
| Unrealized long-term gain | $80,000 |
| Estimated federal tax at 15% on gain | -$12,000 |
| Estimated value after that federal tax | $288,000 |
The estimate may still be incomplete. State tax and the 3.8% Net Investment Income Tax can apply in some situations. Losses elsewhere in the portfolio may offset gains.
For normal net worth tracking, record the current $300,000 market value. For planning a sale, funding retirement withdrawals or estimating spendable wealth, note the embedded gain and potential tax cost.
Hidden Tax Liability #3: Investment Property Depreciation
Rental property investors may focus on property value minus mortgage debt and overlook taxes connected with past depreciation deductions.
Depreciation can reduce taxable rental income during ownership. When depreciated real estate is sold at a gain, part of the gain attributable to depreciation may be treated as unrecaptured Section 1250 gain, which is generally taxed at a maximum federal rate of 25%.
Suppose an investment property has appreciated and the sale includes $60,000 of gain linked to depreciation already claimed. At the maximum 25% federal rate, that portion alone could create an estimated federal tax cost of up to $15,000, before calculating tax on other gain, state tax, selling costs or any applicable Net Investment Income Tax.
This is why property equity and cash received after sale are not always the same number. A rental property may be a strong asset, but a realistic sale-planning calculation should consider mortgage payoff, selling costs and estimated taxes.
Do not apply this treatment casually to a primary home that was never used as depreciable rental or business property. The tax treatment depends on property use and the specific sale details.
Hidden Tax Liability #4: Taxes Already Owed This Year
Future tax consequences belong in an after-tax planning estimate. Taxes already owed are different. They are current liabilities.
Freelancers, sole proprietors, partners, S corporation shareholders and people with substantial income not subject to withholding may need to make estimated tax payments during the year. The IRS generally requires individuals to make estimated payments when they expect to owe at least $1,000 after withholding and refundable credits, subject to the detailed safe-harbor rules.
Suppose a self-employed consultant has set aside $9,000 for quarterly federal tax payments but has not yet paid it. That $9,000 is not available wealth. It should either remain excluded from spendable cash or be recorded as a tax liability until paid.
The same principle applies to state tax already owed, prior-year tax balances and business-related taxes for which you are personally responsible.
How to Account for Taxes in Your Net Worth
Use two versions of your financial picture.
Your standard net worth should list current asset values and current liabilities. Include full account balances for retirement accounts and brokerage assets. Include actual tax amounts currently owed as debts.
Your tax-adjusted planning net worth should go one step further. Estimate future taxes on fully pretax retirement assets, taxable brokerage gains that you plan to sell and investment-property gains where a sale is part of your strategy.
A practical tax review can include:
- Pretax retirement balances marked separately from Roth balances.
- Cost basis and unrealized gains noted for taxable investments.
- Depreciation history reviewed for rental property before a planned sale.
- Current estimated or unpaid tax obligations entered as liabilities.
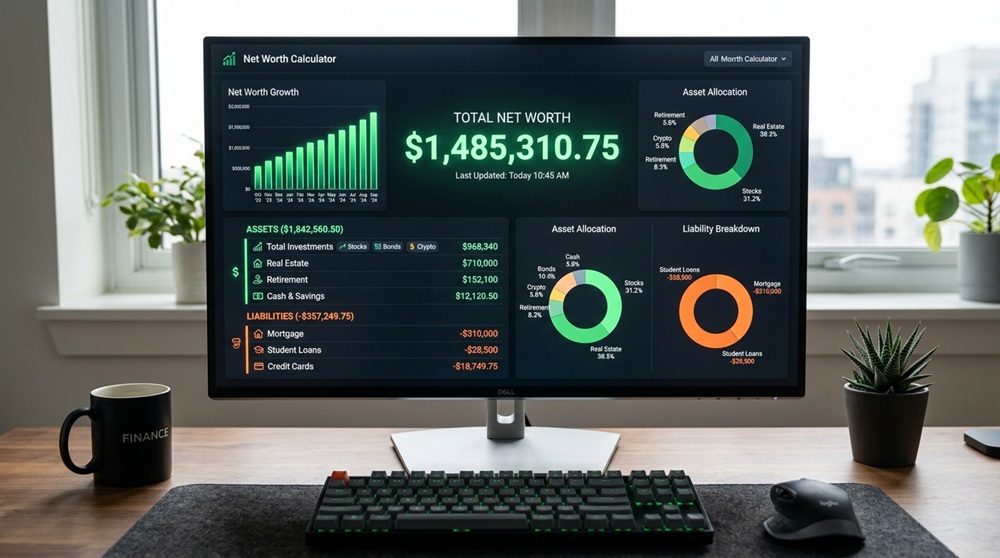
To keep current debts visible, include tax liabilities in your calculation alongside your loans, mortgages and other obligations. The tool includes a tax-liabilities field for taxes currently owed and retirement-account fields for recording current balances. Use your own separate notes or tax professional’s estimate for future embedded taxes that are not currently due.
For more practical resources on measuring assets, liabilities and long-term financial progress, visit NetlyWorth.
Know the Difference Between Your Balance and Your Spendable Wealth
Your standard net worth remains an essential number. It shows the current value of what you own after subtracting debts you owe today.
But when retirement withdrawals, investment sales or property sales are part of your plan, taxes can reduce the money that ultimately supports your lifestyle. Record current tax debt as a liability now. Mark future tax exposure separately. Then make decisions based on the wealth you may actually be able to use, not only the highest number on an account statement.